
 Contacto
 Cómo comprar

Entrega
Guía de compras
 Inglés
 155 b
Hasta 30 días para devoluciones
Clientes que también han comprado


 /
 Tapa blanda
 8.89
€


 /
Tapa blanda
12.89
€


 /
Tapa blanda
13.89
€


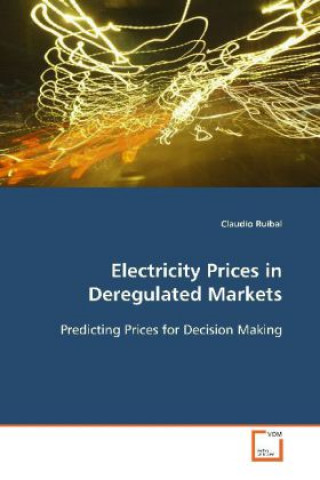
The author outlines a procedure for forecasting the§mean and the variance of the average price of§electricity over a specified time interval in a§deregulated market. Such information would be found§useful in financial forecasts, risk management,§derivative pricing, investment and operational§decisions. It is based on a system model in which the§physical and engineering processes and the bidding§strategies are simultaneously considered. A potential§advantage of this approach is that it can consider§changes in system''s structure over time (e.g., entry§of additional generators or a change in load.) The§emphasis in the current work is on the use of§analytical methods to forecast the statistical§distributions of prices. The estimates of variances§in addition to those of the expected values would§allow computation of prediction intervals for the§price as well as individual firm''s profits, and will§be useful for the purposes of risk management, for§example, in the computation of the Value-at-Risk§(VaR). The system based approach in this work is an§important first step in the construction of a§comprehensive model, which may help to design and§manage electricity deregulated markets.


Sobre el libro
Inglés

Regale este libro hoy
Es fácil
1 Añadir al carrito y elegir Entregar como regalo en el checkout 2 Le enviaremos un vale 3 El libro llegará a la dirección del destinatarioTambién puede interesarle


 /
Tapa blanda
29.69
€
 /
Tapa blanda
19.19
€
 /
Tapa blanda
42.59
€

 /
Tapa blanda
17.39
€


 /
Tapa blanda
28.49
€
 /
Tapa blanda
32.79
€
 /
Tapa dura
41.59
€
 /
Tapa blanda
18.79
€
 /
Tapa dura
16.99
€


¡Hola! Soy Libroamiko, tu asesor de libros.
¿Cómo puedo ayudarte?